Mortgage Solutions Tailored For You
LET'S TALK

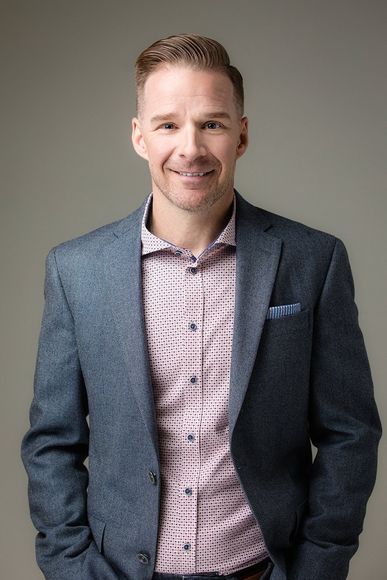
CORY VANCE

Partner & Mortgage Broker at A Better Way Mortgage Group
Mortgage Tips & Insights
Simple tips. Helpful updates.
Smarter mortgage decisions.

About Me

After more than 20 years in financial services, I've learned one important lesson: the right mortgage isn't always the one with the lowest rate.

My approach is built around understanding your needs, providing clear advice, and helping you make confident mortgage decisions that fit both your current circumstances and long-term financial goals.

My 12 years with one of Canada's largest banks gave me a strong understanding of how lenders evaluate mortgage applications, structure financing, and make lending decisions. Today, as a Mortgage Broker, I combine that experience with access to a wide range of banks, credit unions, and national mortgage lenders to help my clients understand their options and find solutions that best suit their needs.

Whether you're purchasing your first home, moving up, investing in real estate, refinancing, or approaching a mortgage renewal, my role is to simplify the process. I take the many available options and narrow them down to solutions that consider not only interest rates, but also flexibility, penalties, cash flow, and your future plans.

I'm also proud to be a Partner with A Better Way Mortgage Group, operating under the Dominion Lending Centres and Mortgage Architects brands. As part of the leadership team, I contribute to an organization with more than 500 mortgage professionals serving clients across Alberta, British Columbia, and Ontario, and over $21 billion in total funded mortgage volume.

Over the years, I've had the privilege of helping hundreds of clients with their mortgage needs, building relationships that often extend across multiple homes, referrals, and stages of life. For me, that's the most rewarding part of this business.

A little about me: Born and raised in Regina, I've called Calgary home since 2000, although my loyalty to the Saskatchewan Roughriders hasn't changed! Outside of work, I enjoy spending time with my wife and our two adult children, getting out on the golf course, and finding new ways to make finances a little less complicated.

At the end of the day, my philosophy is simple: good advice, clear communication, and relationships that last.

If you're buying, refinancing, renewing, or simply looking for an unbiased second opinion on your mortgage options, I'd welcome the opportunity to have a conversation.

CALCULATE

Whether you're just getting started, have a home in mind, or want to refinance or renew an existing mortgage, why not start by using my online calculator? 

CALCULATE

APPLY NOW

You've run some preliminary calculations, you've signed the consent form, the next step is to go through my online mortgage application. 

APPLY

Mortgage Services


MORTGAGE EDUCATION

I believe that in order for clients to feel confident about the mortgage process they need to be educated on all available options. My goal is to guide you through the process so you can make an informed decision.

HOME PURCHASE

If you are looking to buy or build a property, chances are you will need to get a mortgage. With so many options and mortgage products available it is hard to know where to start. I am here to guide you through the process. Why be tied to a single lender when you can have options from several at no cost to you?

RENEWAL OR REFINANCE

If you’re looking to access some of the equity in your home or you have a mortgage that is up for renewal in the next six months, you have options. Often a quick phone call can result in huge savings.

Lenders

I have developed excellent relationships with lenders across the country, let’s figure out which one has the best products for you.

APPLY NOW

MEDIA

I ALWAYS KEEP MY BLOG UP TO DATE SO YOU CAN STAY INFORMED.
By Cory Vance • November 10, 2026
Owning a home feels great—carrying a large mortgage, not so much. The good news? With the right strategies, you can shorten your amortization, save thousands in interest, and become mortgage-free sooner than you think. Here are four proven ways to make it happen: 1. Switch to Accelerated Payments One of the simplest ways to reduce your mortgage faster is by moving from monthly payments to accelerated bi-weekly payments . Instead of 12 monthly payments a year, you’ll make 26 half-payments. That works out to the equivalent of one extra monthly payment each year, shaving years off your mortgage—often without you noticing much difference in your budget. 2. Increase Your Regular Payments Most mortgages allow you to boost your regular payment by 10–25%. Some even let you double up payments occasionally. Every extra dollar goes directly toward your principal, which means less interest and faster progress toward paying off your balance. 3. Make Lump-Sum Payments Depending on your lender, you may be able to make lump-sum payments of 10–25% of your original mortgage balance each year. This option is ideal if you receive a bonus, inheritance, or other windfall. Applying a lump sum directly to your principal immediately reduces the interest charged for the rest of your term. 4. Review Your Mortgage Annually It’s easy to put your mortgage on auto-pilot, but a yearly review keeps you in control. By sitting down with an independent mortgage professional, you can check if refinancing, restructuring, or adjusting terms could save you money. A quick annual review helps ensure your mortgage is always working for you—not against you. The Bottom Line Paying off your mortgage early doesn’t require a massive lifestyle change—it’s about making smart, consistent choices. Whether it’s accelerated payments, lump sums, or regular reviews, every step you take helps reduce your debt faster. If you’d like to explore strategies tailored to your situation—or want a free annual mortgage review—let’s connect. I’d be happy to help you find the fastest path to mortgage freedom.
By Cory Vance • October 28, 2026
On October 28, 2026, the Bank of Canada raised its key interest rate by 0.25%, bringing it to 2.5%. If you have a mortgage, are shopping for a home, or have a renewal coming up, this decision matters. Here is a plain-language look at what changed, why it happened, and what it could mean for you.
By Cory Vance • October 27, 2026
For most Canadians, buying a home isn’t possible without a mortgage. And while getting a mortgage may seem straightforward—borrow money, buy a home, pay it back—it’s the details that make the difference. Understanding how mortgages work (and what to watch out for) is key to keeping your borrowing costs as low as possible. The Basics: How a Mortgage Works A mortgage is a loan secured against your property. You agree to pay it back over an amortization period (often 25 years), divided into shorter terms (ranging from 6 months to 10 years). Each term comes with its own interest rate and rules. While the interest rate is important, it’s not the only thing that determines the true cost of your mortgage. Features, penalties, and flexibility all play a role—and sometimes a slightly higher rate can save you thousands in the long run. Key Questions to Ask Before Choosing a Mortgage How long will you stay in the property? Your timeframe helps determine the right term length and product. Do you need flexibility to move? If a work transfer or lifestyle change is possible, portability may be important. What are the penalties for breaking the mortgage early? This is one of the biggest factors in the real cost of borrowing. A low rate won’t save you if breaking costs you tens of thousands. How are penalties calculated? Some lenders use more borrower-friendly formulas than others. It’s not easy to calculate yourself—get professional help. Can you make extra payments? Prepayment privileges allow you to pay off your mortgage faster, potentially saving years of interest. How is the mortgage registered on title? Some registrations (like collateral charges) can limit your ability to switch lenders at renewal without extra costs. Which type of mortgage fits best? Fixed, variable, HELOCs, or even reverse mortgages each have their place depending on your financial and life situation. What’s your down payment? A larger down payment could reduce or eliminate mortgage insurance premiums, saving thousands upfront. Why the Lowest Rate Isn’t Always the Best Choice It’s tempting to chase the lowest rate, but mortgages with rock-bottom pricing often come with restrictive terms. For example, saving 0.10% on your rate may put a few extra dollars in your pocket each month, but if the mortgage has harsh penalties, you could end up paying thousands more if you break it early. The goal isn’t just the lowest rate—it’s the lowest overall cost of borrowing . That’s why it’s so important to look beyond the headline number and consider the whole picture. The Bottom Line Mortgage financing in Canada is about more than rate shopping. It’s about aligning your mortgage with your financial goals, lifestyle, and future plans. The best way to do that is to work with an independent mortgage professional who can walk you through the fine print and help you secure the product that truly keeps your costs low. If you’d like to explore your options—or review your current mortgage to see if it’s really working in your favour—let’s connect. I’d be happy to help.
MORE ARTICLES
Cory has been providing mortgage advice to me and my family as well as my clients for many years. What has always impressed me is his prompt personal service, “get it done attitude”, and he not only meets but often exceeds tight timelines facilitating a worry-free experience.
Cory is a well-respected industry leader and demonstrates this when providing valuable knowledge from his long background in financial services. He takes a personal interest in every client and is a great communicator with all parties involved creating a smooth transaction for all.

ROD B (REALTOR)
John Doe's Image
In a word, our experience with Cory was outstanding. Considerations were explained clearly with progress communicated consistently and honestly right through to closing. We were extremely pleased with the end result and would not hesitate to recommend both Cory and his team at Dominion Lending Centres – A Better Way.

ANDREW G

John Doe's Image
We have worked with Cory Vance and Nicole deBoer for four mortgages that have included primary residences, as well as, rental properties. Cory and Nicole’s advice is excellent, they have many contacts with different banks and credit unions and have consistently secured interest rates from lenders that were lower than we were able to ourselves. When you are a client of Cory and Nicole’s, the process of applying for and obtaining a mortgage is very straightforward. They know exactly what documents you need and the right questions to ask to make sure you obtain the best mortgage product for your needs. They are also super helpful in the application process making sure forms are filled out correctly and advocating if necessary.
We expected Cory and Nicole to be excellent and they surpassed that expectation. We are grateful for both the mortgages and the properties they have secured us and we cannot recommend them enough and know we will be working with them again in the future.

ADELE
